
0% processing fees with EDGE.
Your customer covers the small fee.
EDGE is MidPay's dual pricing program, powered by Payanywhere/North. Your business pays 0% — the terminal shows a cash price and a card price side by side, and the customer picks which one to pay. $0 monthly, $0 setup, no contracts, and the same terminals you already use.
Clearly disclosed at checkout. Debit cards handled correctly. Fully within card-network rules.

Processing that costs the business nothing
Most businesses treat card-processing fees as an unavoidable tax on every sale. EDGE — MidPay's dual pricing program, powered by Payanywhere/North — flips that. Instead of the merchant absorbing the cost of card acceptance, the terminal shows a cash price and a card price side by side, and the customer decides which one to pay. When they pay the card price, your processing cost on that sale is exactly 0%.
This is a compliant surcharge model, not a hidden markup. The fee is disclosed up front, capped within card-network limits, and applied only to credit-card payments — debit cards are handled separately and correctly. Nothing is buried, nothing is bolted on after the fact. Your customer sees the line item before they tap, dip, or key in a card, the same way they would see sales tax.
For a business doing real volume, the math is hard to ignore. If you process $30,000 a month in card sales and were paying roughly 2.7% on credit, that is about $810 every month flowing out the door in fees — close to $9,700 a year. Under EDGE, that line goes to zero. The savings do not trickle in; they show up on day one.
Three steps. No new habits to learn.
EDGE runs on the same hardware and the same checkout flow you already know. The only thing that changes is who covers the card fee.
Customer sees a small fee
At checkout, a clearly labeled 4% convenience fee appears on the card total — on the terminal screen, the online cart, or the printed receipt. It is shown before payment, never sprung afterward.
They choose to pay it — or pay cash
The customer decides. Paying by card covers the small fee; paying with cash skips it entirely. Either way the choice is theirs, and either way you collect the full price of what you sold.
You keep 100% of the sale
The convenience fee covers the cost of card acceptance, so your processing rate on that sale lands at 0%. Your deposit is the full ticket — not the ticket minus a percentage.
Pick the terminal, apply for EDGE
EDGE runs on Payanywhere hardware built for dual pricing right on the screen — the customer sees both prices before they tap, dip, or swipe.
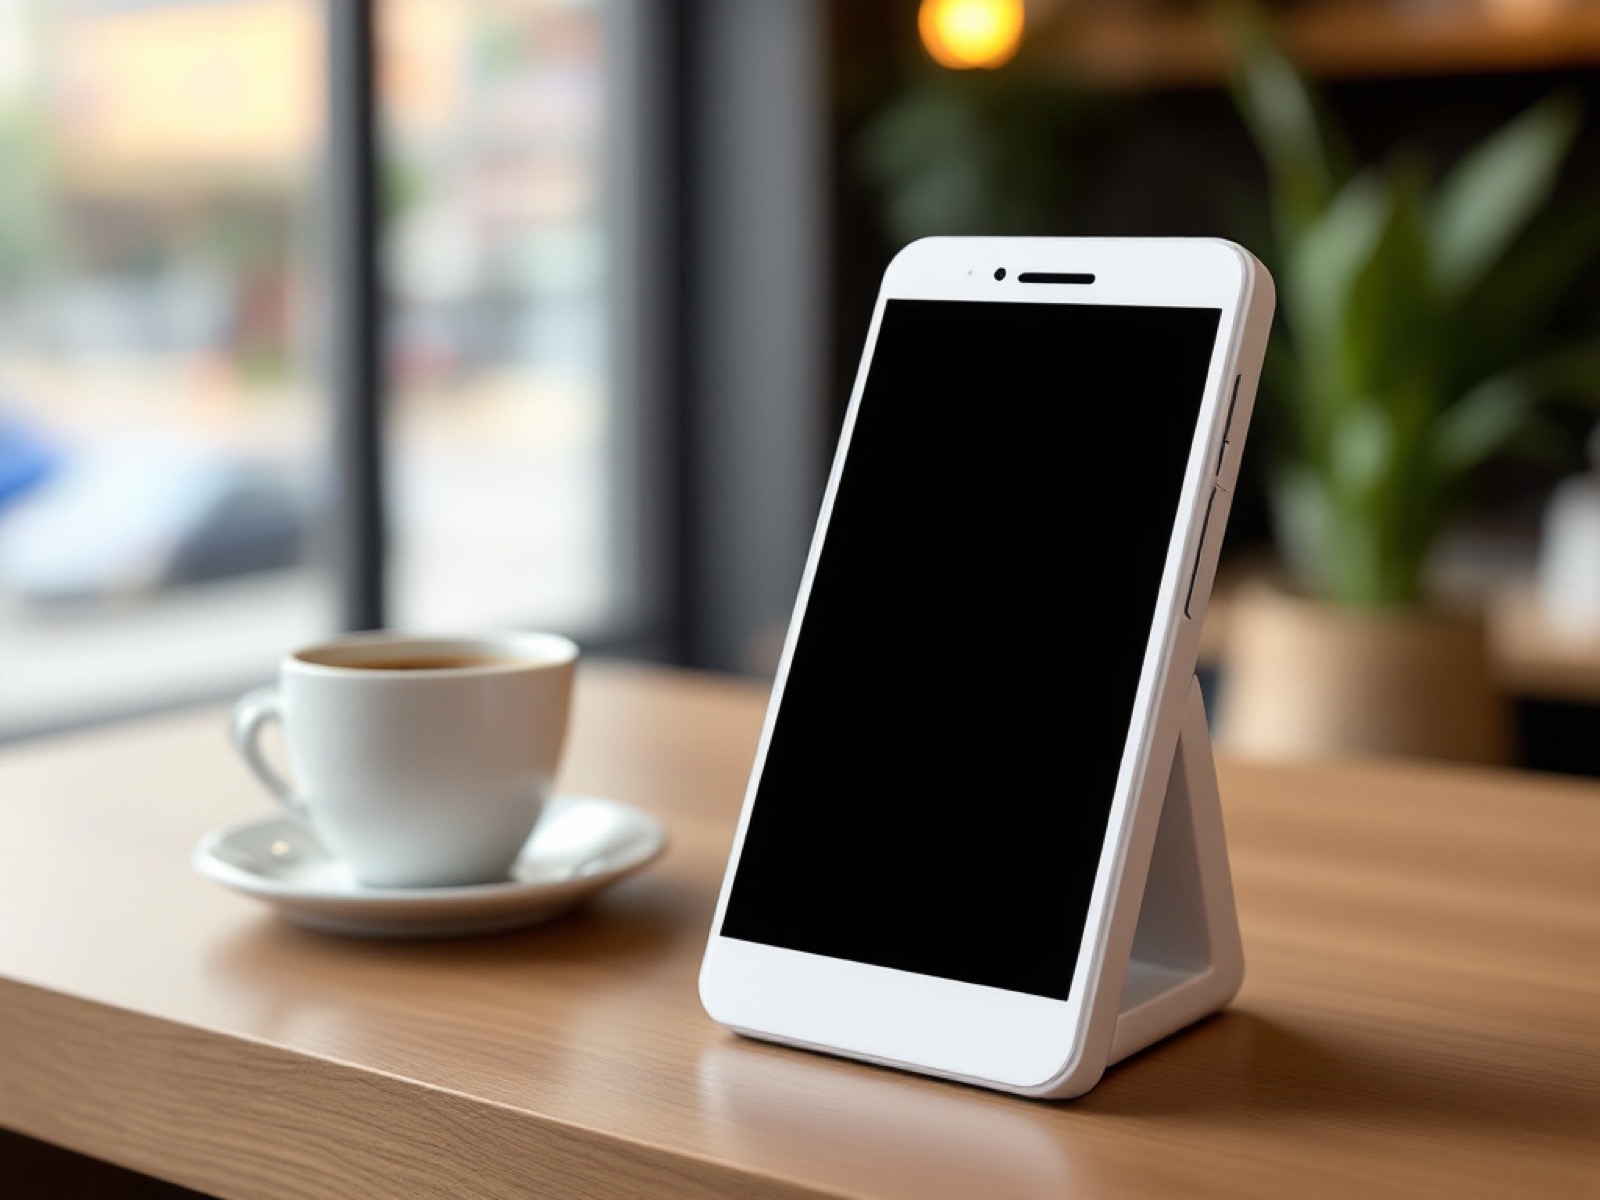
EDGE Smart Terminal (A920 Pro)
PAX A920 Pro — 5.5" display, handheld, with a built-in printer. Runs EDGE dual pricing on the same screen your customer checks out on.
Apply for EDGE with this terminal →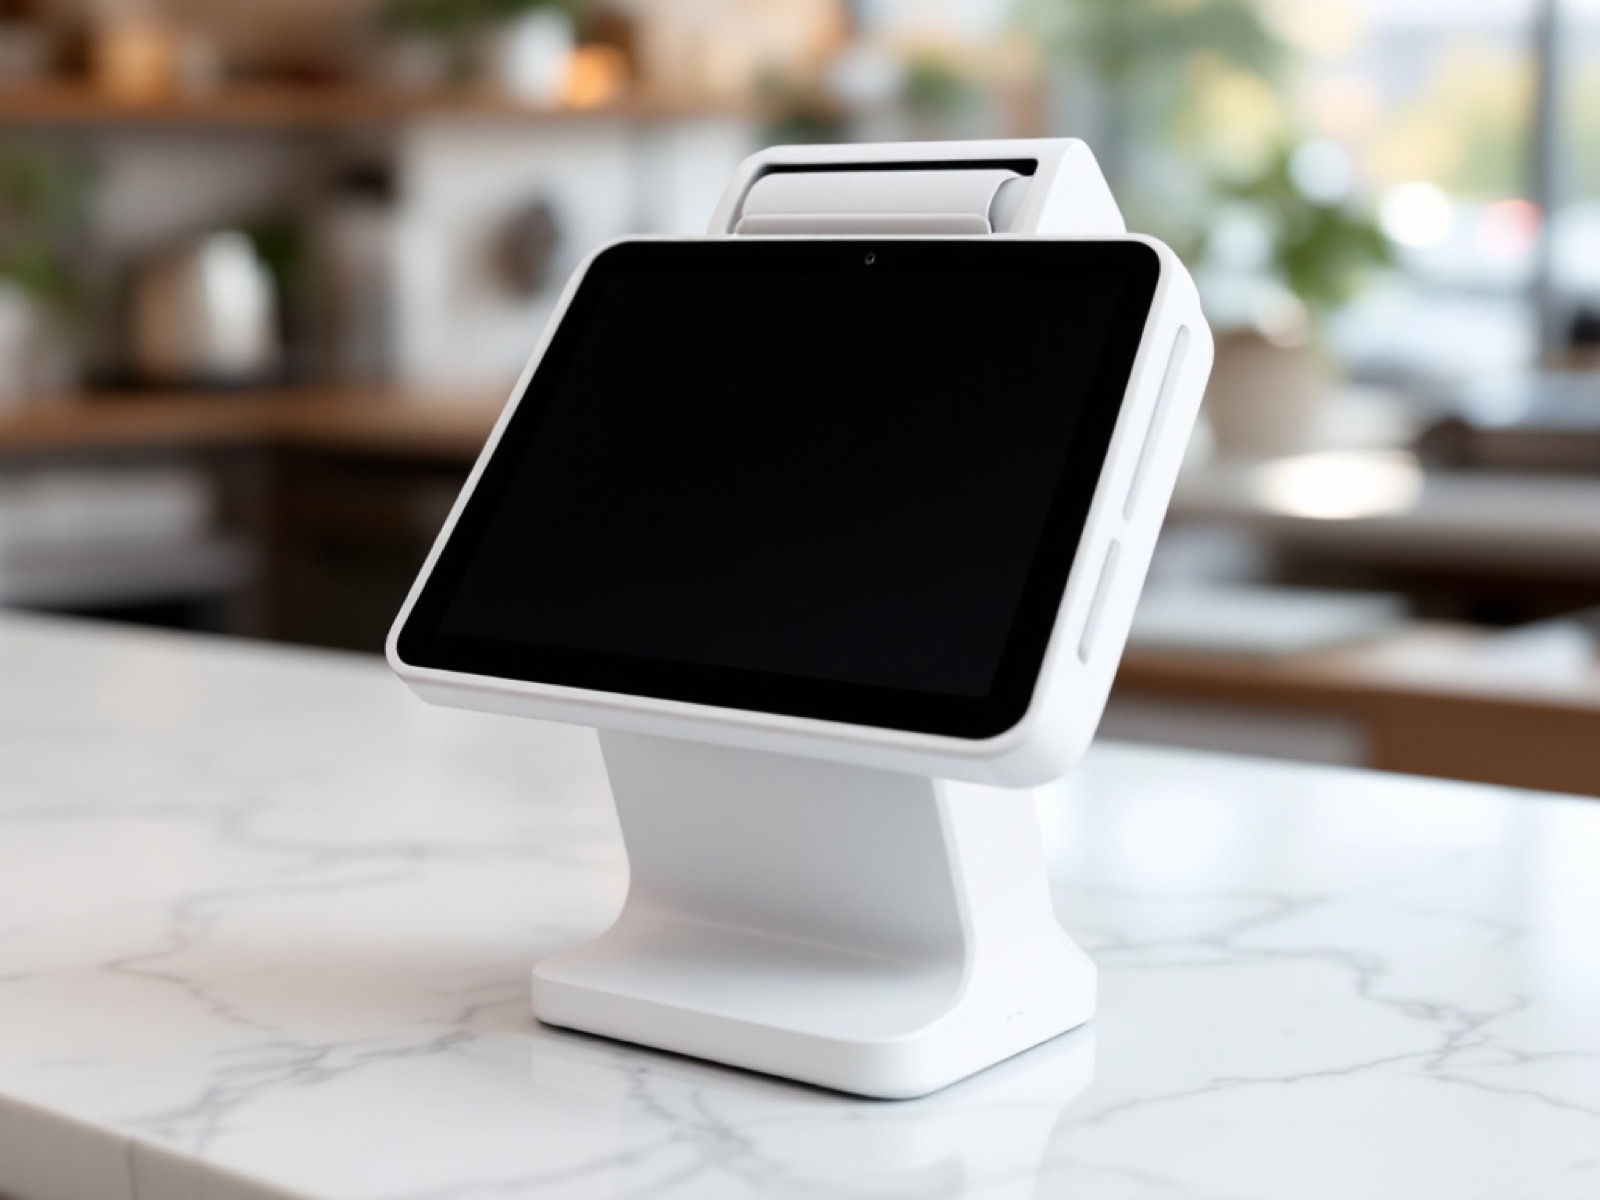
EDGE E600 PA Terminal (Smart Flex)
PAX E600 — 8" display, handheld or countertop, with a built-in printer. Same EDGE dual pricing, sized for a busier counter.
Apply for EDGE with this terminal →Square does not offer a 0% merchant option
Square is a solid product, but its standard pricing always keeps the fee on the business. Square charges 2.6% + 10¢ for in-person tap, dip, and swipe, 2.9% + 30¢ for online payments, and 3.5% + 15¢ for manually keyed cards. There is no built-in customer-pays surcharge program in Square's standard offering — the percentage comes out of your sale, every time. That is the gap MidPay EDGE was built to close.
A $50 in-person card sale
You keep the full ticket
Your merchant fee on the sale is 0%. The customer covers a small $2.00 convenience fee (4%), shown clearly at checkout, and you deposit the entire $50.
Fee comes out of your sale
Square's in-person rate of 2.6% + 10¢ takes about $1.40 from the $50 sale. There is no standard option to pass that cost to the customer instead.
Rates shown are each provider's publicly published pricing. Square's in-person rate is 2.6% + 10¢; online is 2.9% + 30¢; manually keyed is 3.5% + 15¢. MidPay also offers Simple Pricing at 1.49% debit and 2.69% credit, or a flat 2.69%, if a customer-pays model is not the right fit. The right choice depends on your average ticket and how your customers pay.
Built to keep more of what you earn
Keep 100% of sales
Your processing cost on card sales is 0%. The full ticket lands in your account instead of arriving short by a percentage.
Same terminals
No new hardware to buy or learn. EDGE runs on the equipment you already have, with the checkout flow your staff already know.
Transparent & compliant
The fee is disclosed at checkout, capped within network rules, and applied only where it is allowed. Debit cards are handled correctly.
$0 monthly, $0 setup
No monthly fee, no setup fee, and no long-term contract. If EDGE stops fitting your business, you can change programs anytime.
Dual pricing has real signage requirements — at the door, at the register, and on the receipt — plus a few state-specific rules. MidPay sets EDGE up inside those rules and keeps your disclosure compliant. See exactly what has to be posted, where, and in what size in our dual pricing signage guide.
EDGE, in plain terms
Is a customer-pays surcharge program legal and compliant? +
Yes. Surcharging credit card transactions is permitted across most of the United States when it is disclosed clearly and kept within card-network limits. MidPay sets your program up inside those rules: the fee is shown to the customer before they pay, it stays within network caps, and debit cards are handled correctly and never surcharged where prohibited. We keep the disclosure and signage compliant so you do not have to track the fine print yourself. If your state or situation calls for a different model, we will tell you up front and point you to one of our flat-rate plans instead.
Will customers mind paying the small fee? +
Most do not, because the fee is small, optional, and clearly explained. On a $50 sale it is about $2, and the customer can pay it on the card or simply pay with cash to skip it entirely. Customers already see convenience fees at gas pumps, ticket sites, and government offices, so the concept is familiar. Businesses that move to EDGE typically see little to no change in how customers check out — while keeping the full ticket on every card sale. Clear signage at the register and a labeled line item at checkout do most of the work.
Can I switch between MidPay programs anytime? +
Yes. There are no contracts and no early-termination fees with MidPay. If EDGE is not the right fit, you can move to Simple Pricing — 1.49% debit and 2.69% credit — or to our flat 2.69% rate whenever you like. Your hardware, your account, and your deposits stay the same; only the way the fee is handled changes. Many businesses start on EDGE to keep costs at zero, then adjust as their average ticket and customer mix change. You are never locked in.
Stop paying to get paid.
Switch to EDGE and keep 100% of every sale. $0 monthly, $0 setup, no contracts — and you can change programs anytime.